By Ken Gardner | MexPat Guide
Before a move, make a record of what you own, where your income comes from and which major transactions are approaching.
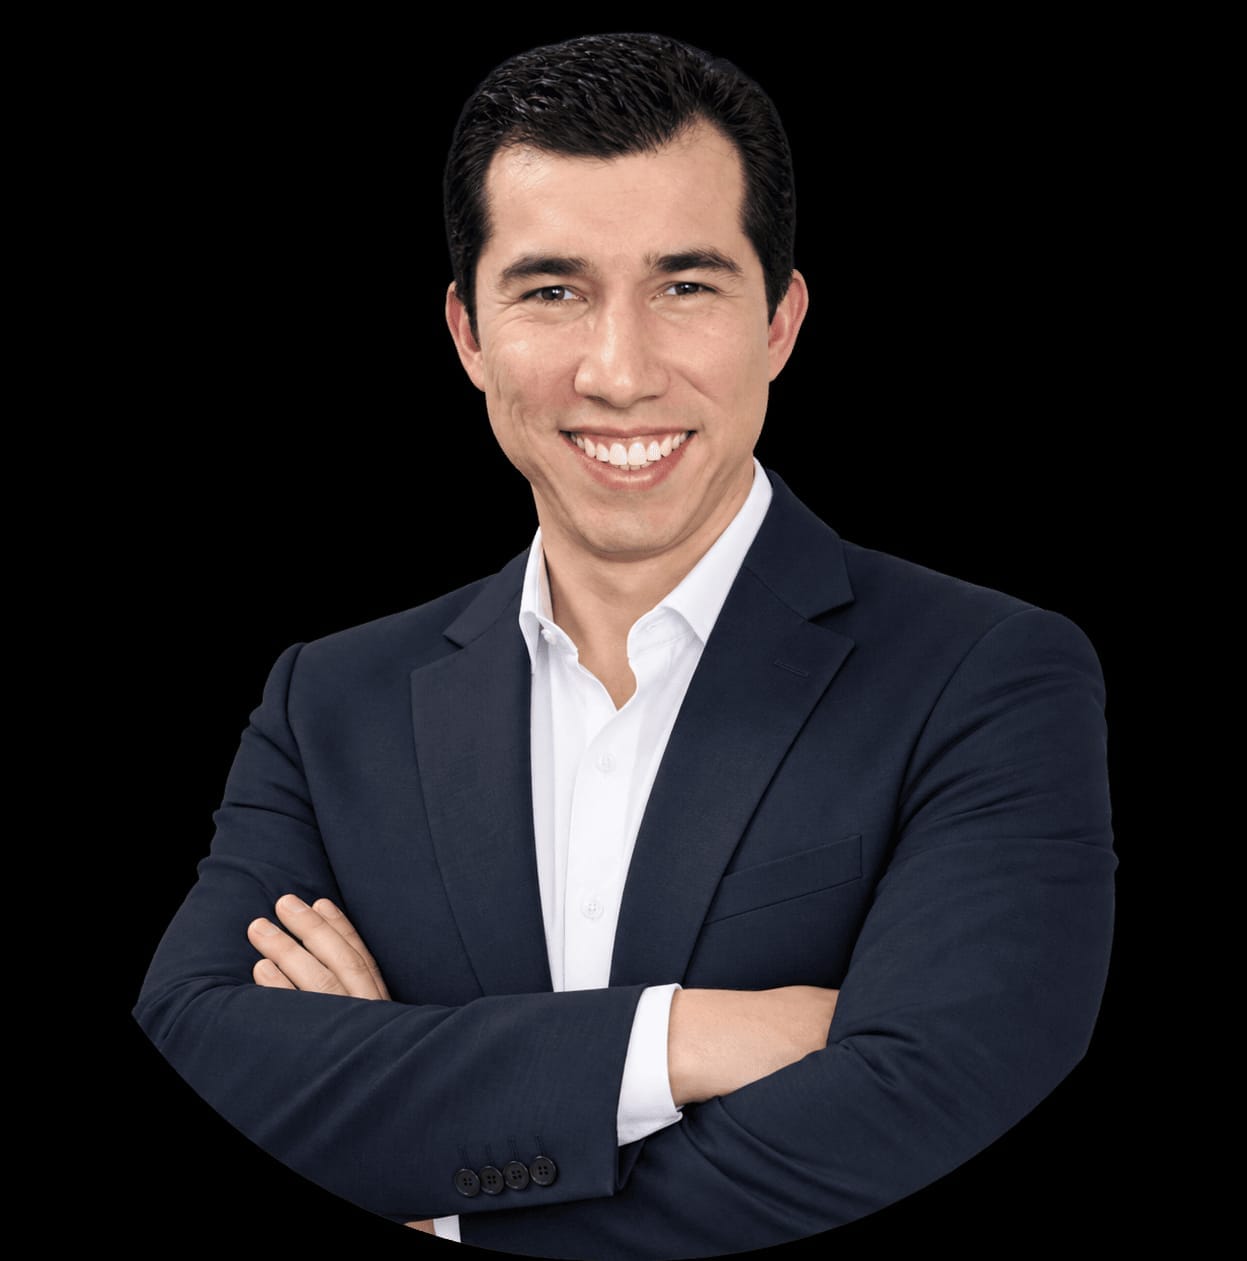
Fernando Camacho Limón, a public accountant and founder of Camacho Limón Contadores, explains how to prepare for a useful tax consultation before moving to Mexico. His starting point is the history of your money, followed by your tax residence, future income and the timing of major decisions.
The answers below were translated from Fernando’s written Spanish responses and lightly edited for clarity. Fernando reviewed and approved the interview before publication.
1. What should someone review with a tax adviser before moving money to Mexico?
Fernando: Before transferring a significant amount, I would first look at where those funds came from, whether their origin is lawful and legitimate, and how they were treated for tax purposes in the country where they were generated.
It is also important to explain how that wealth was accumulated and keep supporting documents, such as bank statements, tax returns, payslips, contracts and records of asset or investment sales.
For example, someone might have lived in the United States for many years and accumulated US$1 million through work, investments and savings, then moved to Mexico and transferred part of that money. The transfer itself does not necessarily generate a tax in Mexico. What matters is being able to show that the money was already part of their assets, where it came from and when it was generated.
I would then review their tax position in Mexico, including whether they will be a tax resident or non-resident. That can change the treatment of income they continue receiving after the move.
Before moving money, understand its origin, legitimacy, traceability and previous tax treatment.
2. How is immigration residence different from tax residence?
Fernando: They are two different things. Immigration residence concerns the status under which a foreign national can legally live in Mexico and, depending on the circumstances, whether they have permission to work.
Tax residence determines how that person is treated for tax purposes. In general, a Mexican tax resident is taxed here on income even when it is generated in another country.
Article 9 of Mexico’s Federal Fiscal Code starts with whether a person has a home in Mexico. If they also have a home in another country, the analysis can involve their centre of vital interests, including where most of their income arises or where their principal professional activities take place.
A common misunderstanding is that temporary or permanent immigration residence automatically means tax residence. Not necessarily: they are separate analyses.
3. What information makes the first consultation useful?
Fernando: The most important thing is to understand how the person’s economic life will work between Mexico and the other country.
Where will they physically work? Who will pay them: a Mexican business, a foreign business or both? In which country will they receive the money, and roughly how much income do they expect?
We also need to know about rental or Airbnb income, dividends, interest, pensions, investments, property sales and interests in companies. It is particularly important to flag a planned property sale, severance payment or other major transaction close to the move.
Other useful details include time planned in each country, whether family will move too, whether a home will be retained abroad, permission to work in Mexico and continuing tax obligations in the country of origin.
Useful documents normally include recent tax returns, proof of income, significant bank statements, investment and pension information, property documents and details of companies in which the person has an interest.
The first consultation is not about reviewing every document individually. It is about understanding the overall picture and identifying what needs deeper analysis.
4. What changes for a pensioner, a remote worker or a business owner?
Fernando: Quite a lot. For someone living on a pension who no longer works, I would start with the type of pension, the country it comes from and who pays it. Is it a private pension, social-security pension or government pension? We would also review tax residence and whether a double-taxation treaty applies, because that can affect how it is taxed under the rules of the countries involved and any applicable treaty.
For someone working remotely from Mexico, the physical location of the work matters, as do who they work for, who pays them, where the employer is located and their tax residence.
For a business owner, the analysis is broader. Do they operate as an individual or through a company? Where is it incorporated and managed? Where are its customers, employees and assets? What interest does the person hold, and how do they receive profits?
In all three cases, the underlying questions are the same: what kind of income is involved, where it arises, who pays it and how it is taxed under the rules of the countries involved and any applicable treaty.
5. How should advisers in the two countries work together?
Fernando: Ideally, they should work together using the same information: the person’s tax residence, income, where it arises, who pays it and what tax is already being paid or withheld in each country.
Agree from the start which issues each adviser will review. Share relevant returns, withholding records and evidence of tax paid.
The aim is not only to avoid double taxation, but also to manage the total tax burden lawfully, using treaties, tax credits, deductions, exemptions and other benefits where the laws of both countries permit them.
The advisers should work as a team so the person complies correctly and pays the tax they are legally required to pay.
6. What mistake could people prevent before the move?
Fernando: A common mistake is moving first and reviewing tax matters afterwards. By then, someone may already have sold a property, liquidated investments, received a termination payment or started a new job without considering the tax effect of changing countries.
Many of these situations can be anticipated. I would put the preparation into three steps:
1) Establish a clear picture of your income, investments, properties, companies and accumulated assets before the move, along with continuing obligations in your country of origin.
2) Identify significant upcoming transactions: selling a house, apartment, land or car; liquidating shares, funds or other investments; receiving dividends, bonuses or severance; starting a job; changing how salary is received; selling a business; or receiving another substantial amount near the move. The treatment can change depending on whether the transaction takes place while you are still tax resident in one country or have become resident in the other.
3) Coordinate the Mexican adviser with the adviser in your country of origin to review tax residence, treaties, taxes paid, credits, deductions and lawful alternatives for carrying out those transactions more tax-efficiently.
The point is to plan ahead. In international tax matters, the timing of a transaction can be as important as the transaction itself.
About Fernando Camacho Limón
Fernando Camacho Limón is a public accountant and founder of Camacho Limón Contadores. He has worked in tax for more than 13 years and currently specializes in advising expatriates and people with tax affairs spanning Mexico and other countries, particularly tax residence, international income and compliance in Mexico.
Fernando Camacho Limón | Contador Público | Especialista en impuestos para expatriados | Camacho Limón Contadores

About the Author
Ken Gardner develops and curates MexPat Guide from Vancouver, Canada. He focuses on Mexico relocation research and practical comparison questions. This is educational planning information, not a claim of local residence or individual immigration advice.
Published